
The year you were born decides your FRA, and nothing else does — not when you stop working, not when you file. Once you know yours, three choices hang off it: the permanent cut for claiming early, the delayed retirement credit you earn for waiting, and the break-even age that decides whether waiting actually pays off. To run your own figures against it, the free claiming-age table covers one person and the claiming-age calculator ($7.95) covers a couple.
Full retirement age by birth year
Full retirement age depends only on the year you were born. A birthday on January 1 counts as the previous year's row — Social Security treats you as reaching an age the day before your actual birthday, not on it (POMS GN 00302.400), which is what pushes a January 1 birthday back one row.
| Born | Full retirement age |
|---|---|
| January 2, 1943 – January 1, 1955 | 66 |
| January 2, 1955 – January 1, 1956 | 66 and 2 months |
| January 2, 1956 – January 1, 1957 | 66 and 4 months |
| January 2, 1957 – January 1, 1958 | 66 and 6 months |
| January 2, 1958 – January 1, 1959 | 66 and 8 months |
| January 2, 1959 – January 1, 1960 | 66 and 10 months |
| January 2, 1960 or later | 67 |
Source: POMS RS 00615.003.
What full retirement age actually does
FRA isn't just a number on a chart — it's the reference point four separate pieces of Social Security arithmetic are measured from:
- The early-claiming reduction is measured from it. Claim before FRA and the cut is 5/9 of 1% for each of the first 36 months early, then 5/12 of 1% for each month beyond that (POMS RS 00615.101). With an FRA of 67, claiming at 62 is 60 months early — a 30% cut, so 70% of the full benefit is payable. With an FRA of 66, claiming at 62 is 25% off.
- Delayed retirement credits are measured from it. Wait past FRA and a worker's own benefit grows by 2/3 of 1% per month — 8% a year — from the FRA month up to age 70, when credits stop (POMS RS 00615.692, POMS RS 00615.690). That's a maximum of 32% more at an FRA of 66, or 24% more at an FRA of 67. Credits generally take effect the January after the year they were earned, or at 70. They raise the worker's own benefit and, eventually, the survivor benefit — they never raise a spousal benefit (POMS RS 00615.695: "DRCs only increase the NH's RIB").
- The spousal 50% is measured at it. A spousal benefit tops out at 50% of the worker's FRA benefit, and a spouse only reaches that ceiling once they themselves have reached their own FRA (POMS RS 00615.201). Claimed early, it's reduced too: 25/36 of 1% for each of the first 36 months early, 5/12 of 1% beyond that — a spouse with an FRA of 67 claiming at 62 gets 32.5% of the worker's FRA benefit, not 50%. Deemed filing applies to anyone born on or after January 2, 1954 (POMS GN 00204.035).
- The earnings test stops at it. Working while claiming before FRA can withhold benefits: for 2026, $1 for every $2 earned over $24,480 in a year spent entirely under FRA, or $1 for every $3 over $65,160 in the year FRA is reached, counting only earnings before the FRA month (POMS RS 02501.025). Once FRA is reached, the test no longer applies, and any months it withheld earlier are credited back into the benefit.
What full retirement age is not
FRA gets confused with three other ages, and the differences matter:
- It is not the earliest age you can claim. That's 62, for anyone (POMS RS 00201.001) — entitlement requires the whole month at 62 unless you were born on the 1st or 2nd of the month. FRA is when the reduction for claiming early stops applying, not when eligibility starts.
- It is not automatically the best age to claim. Delayed retirement credits keep adding to a worker's own benefit for every month past FRA, up to 70. Which age actually pays out more over a lifetime depends on how long the benefit ends up being paid — a break-even question, not something FRA alone settles.
- It is not the same as survivor full retirement age. Survivor FRA follows its own birth-year schedule (POMS RS 00615.003, section B), and its steps land two birth years later than the retirement schedule: born 1945 through 1956, 66; 1957, 66 and 2 months; 1958, 66 and 4 months; 1959, 66 and 6 months; 1960, 66 and 8 months; 1961, 66 and 10 months; 1962 or later, 67. So the two ages are identical for many birth years, and where they differ the survivor age is the earlier one — someone born in 1958 reaches their own FRA at 66 and 8 months but their survivor FRA at 66 and 4 months. It is never later than a person's own retirement FRA, and never past 67. Survivor benefits can start as early as 60, reduced up to 28.5% (71.5% at 60), and are capped by the widow(er)'s limit — the larger of the deceased's reduced benefit or 82.5% of their primary insurance amount, when the deceased had claimed early (POMS RS 00615.320). Deemed filing does not apply to survivors, so a widow or widower can take a reduced survivor benefit first and switch to their own, unreduced benefit later — a sequencing move the worker's own and spousal rules don't allow.
Where the claiming-age calculator fits
Full retirement age is the fixed point; almost everything else in a claiming decision is a choice measured against it. The Social Security Claiming-Age Calculator applies these exact rules — the early reduction, delayed credits, spousal 50% and the earnings test — and scores all 81 claiming-age pairs a couple could choose, with the spousal top-up and survivor step-up counted and a plan tested against 49 death-age scenarios. Every rule it applies is named on its own tab with the POMS section it comes from. It never estimates a benefit for you — you type the figure from your own Social Security statement, and it works out the rest.
The usual alternatives are a blank spreadsheet you build the reduction and credit formulas into yourself, or a $49–$144-a-year retirement-planning subscription (2026 prices) that runs the same arithmetic for as long as you keep paying for it. The calculator sits between the two at $7.95, once: a file you own, that computes your full retirement age and every claiming age from 62 to 70 the same way every year a new statement arrives, with the rules it follows named and cited on their own tab instead of hidden behind someone else's login.
If you just want to see one person's numbers at every age first, the free Social Security Claiming-Age Table runs the same reduction and delayed-credit arithmetic for a single person from the birth date and FRA benefit you type in — no email, no signup. It is a spreadsheet you download and fill in on your own machine, not a form you submit online.
Templates that implement this
Calculators built on this reference point
1 template
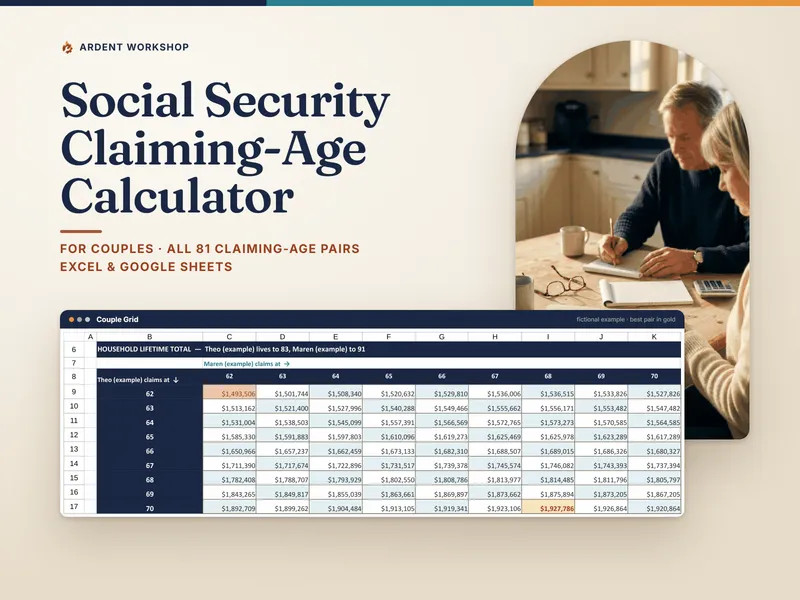
The Social Security Claiming-Age Calculator computes your full retirement age from your birth year automatically, then runs every claiming age from 62 to 70 — for one person or a couple — against it.
Frequently asked questions
- What is full retirement age (FRA)?
- Full retirement age is the age at which Social Security pays your full, unreduced retirement benefit — 100% of your primary insurance amount, with no early reduction applied. It is set by your birth year, it runs from 66 to 67 depending on when you were born, and it is the single reference point the rest of the claiming-age math is measured from: how much claiming early costs you, how much waiting adds, and how big a spousal benefit can be.
- What is my full retirement age based on my birth year?
- Anyone born January 2, 1943 through January 1, 1955 has a full retirement age of 66. It then rises by two months for each birth year after that — 66 and 2 months for 1955, 66 and 4 months for 1956, 66 and 6 months for 1957, 66 and 8 months for 1958, and 66 and 10 months for 1959 — until it reaches 67 for anyone born January 2, 1960 or later (POMS RS 00615.003). A birthday on January 1 counts as the previous year for this purpose, and Social Security treats you as reaching an age the day before your birthday, not on it (POMS GN 00302.400).
- Is full retirement age the same as the earliest age I can claim Social Security?
- No. The earliest age you can claim a retirement benefit is 62, regardless of your full retirement age — you just take a permanent reduction for claiming before FRA. FRA is the age you get the unreduced amount, not the age you become eligible.
- Is full retirement age the best age to claim Social Security?
- Not automatically. FRA is the age your check stops being reduced for claiming early, but delayed retirement credits keep adding to a worker's own benefit for every month you wait past FRA, up to age 70 — so for many people the largest monthly check comes from waiting past FRA, not from claiming at it. Which age actually comes out ahead over a lifetime depends on how long you expect to receive the benefit, which is a break-even question, not something FRA alone answers.
- Is survivor full retirement age the same as my own full retirement age?
- Not always, and never later. Survivor full retirement age follows its own birth-year schedule, whose steps land two birth years later than the retirement schedule — so for many birth years the two ages are identical, and where they differ the survivor age is the earlier of the two. It is never later than your own retirement full retirement age, and never past 67. The survivor schedule runs: born 1945 through 1956, 66; 1957, 66 and 2 months; 1958, 66 and 4 months; 1959, 66 and 6 months; 1960, 66 and 8 months; 1961, 66 and 10 months; 1962 or later, 67 (POMS RS 00615.003, section B). Someone born in 1958, for example, reaches their own full retirement age at 66 and 8 months but their survivor full retirement age at 66 and 4 months. Survivor benefits can also start earlier, at 60, at a reduction of up to 28.5%, so 71.5% of the full amount is payable at 60 (POMS RS 00615.301). And a rule that applies to your own and spousal benefits does not apply to survivor benefits: there is no deemed filing for survivors, so a widow or widower can take a reduced survivor benefit first and switch to their own, unreduced benefit later (or the reverse), a sequencing choice that is not available on the worker's own record.
- What happens to my Social Security check if I claim before full retirement age?
- It is reduced, permanently, and the reduction is measured from FRA: 5/9 of 1% for each of the first 36 months you claim early, then 5/12 of 1% for each additional month beyond that (POMS RS 00615.101). Claiming at 62 with an FRA of 67 is 60 months early, which comes to a 30% cut — you would be paid 70% of your full benefit. With an FRA of 66, claiming at 62 is 48 months early, a 25% cut.
- What happens if I wait past full retirement age to claim Social Security?
- Your own benefit grows: delayed retirement credits add 2/3 of 1% for every month you wait past FRA, which comes to 8% a year, up to age 70 — waiting past 70 adds nothing further (POMS RS 00615.692). That works out to a maximum of 32% more for someone with an FRA of 66, or 24% more for someone with an FRA of 67. Delayed credits raise a worker's own benefit and, later, a survivor's benefit — they never raise a spousal benefit (POMS RS 00615.695).
- Does full retirement age affect my spousal benefit?
- Yes — a spousal benefit is measured as up to 50% of the worker's FRA benefit, and that 50% ceiling is reached only if the spouse claiming it has also reached their own full retirement age (POMS RS 00615.201). Claim the spousal benefit early and it is reduced too: 25/36 of 1% for each of the first 36 months early, then 5/12 of 1% beyond that. A spouse with an FRA of 67 claiming at 62 gets 32.5% of the worker's FRA benefit rather than 50%.
- Does the Social Security earnings test stop at full retirement age?
- Yes. The earnings test only applies to someone who has claimed before FRA and is still working. For 2026, if you are under FRA all year, Social Security withholds $1 in benefits for every $2 you earn over $24,480; in the calendar year you reach FRA, it withholds $1 for every $3 over $65,160, counting only earnings before the month you reach FRA (POMS RS 02501.025). Once you reach FRA the test stops applying entirely, and any months withheld earlier are credited back into your benefit at that point.