
A delayed retirement credit is the one part of a Social Security benefit you can still change after your earnings record is set: it is paid for waiting, it accrues month by month, and it stops dead at 70. Credits are measured from full retirement age, so that is the term to be sure of first. The free Social Security Claiming-Age Table shows the benefit at every age from 62 to 70 — reduced below full retirement age, credited above it; the paid Social Security Claiming-Age Calculator ($7.95, once) does the same for one person or a couple.
How the credit is calculated
Social Security adds 2/3 of 1% for every month you wait to claim past your full retirement age (FRA), which works out to 8% for a full year of waiting. The rule applies to anyone born after January 1, 1943, and credits are earned from your FRA month through the month before you turn 70 (POMS RS 00615.692 and POMS RS 00615.690).
Why the maximum differs by full retirement age
The cap isn't the same for everyone, because it's set by how many months sit between your FRA and 70 — and FRA itself steps up by birth year, from 66 to 67 (POMS RS 00615.003). Anyone with an FRA of 66 (born January 2, 1943 through January 1, 1955) has 48 months to earn credits, for a maximum of 32%. Anyone with an FRA of 67 (born January 2, 1960 or later) has only 36 months, for a maximum of 24% — 12 fewer months at 2/3 of 1% each.
Credits stop at 70, and don't show up until the following January
Two timing details catch people out. First, credits stop accruing the month before you turn 70 — waiting past 70 adds nothing, because Social Security doesn't recognize any further delay after that point (POMS RS 00615.690). Second, a credit generally takes effect the January after the year it was earned — or at 70, if you're already claiming by then — so a credit earned partway through a year doesn't change that year's check; it shows up starting the following January. The payment itself is then rounded down to the whole dollar (POMS RS 00601.020).
What delayed retirement credits raise — and the one thing they never do
DRCs raise the worker's own retirement benefit, and POMS RS 00615.695 is explicit that this is all they raise: "DRCs only increase the NH's RIB." Because a surviving spouse is paid 100% of what the worker was receiving, DRCs included, delaying also raises the survivor benefit a widow or widower would later collect (POMS RS 00615.301).
What DRCs never do is raise a spousal benefit. A spouse claiming on a worker's record is paid up to 50% of the worker's FRA benefit, full stop — that ceiling doesn't move no matter how long the worker waits past FRA (POMS RS 00615.201). This is the part that is easiest to get backwards: waiting helps the worker's own check and, eventually, a widow or widower's check — it does nothing for a spouse's check paid while the worker is still alive.
A worked example: what the credit is worth in dollars
Theo is the workbook's fictional example — his figures are illustrative, not anyone's real record. His full retirement age is 67 and his FRA benefit — the figure he read off his own statement — is $2,860 a month. Waiting one year past FRA, to 68, adds 12 months of credit: 12 × 2/3 of 1% = 8%, so $2,860 × 1.08 rounds down to $3,088. Waiting the full three years to 70 adds 36 months: 36 × 2/3 of 1% = 24%, the maximum available at his FRA, so $2,860 × 1.24 rounds down to $3,546. For contrast, claiming early at 62 — a reduction, not a credit — pays him $2,013. (Claiming at 62 on an FRA of 67 is a 30% cut at the full 60 months early. Entitlement needs the whole month at 62 unless you were born on the 1st or 2nd, so Theo's first payable month falls 59 months before his FRA rather than 60, and his reduction lands just under 30% — POMS RS 00201.001.) The distance between $2,013 and $3,546 is the entire claiming-age decision in one person's numbers; the calculator runs it for both people in a couple, against every age each of them could claim.
Where to go next: full retirement age, break-even and the workbook
A delayed retirement credit only means something measured against full retirement age, which is where the credits start accruing, and whether waiting actually pays off over a lifetime is a break-even question, worked by hand in a separate walkthrough.
Try the free Social Security Claiming-Age Table first — a single-person table of the benefit at every age 62 to 70 from one FRA figure, ungated, one click. It is a spreadsheet you download and fill in on your own machine, not a form you submit online. When the decision involves a second person, the Social Security Claiming-Age Calculator takes it up to a couple, with every rule on this page shown on its own Rules tab and cited to its POMS section. A retirement-planning subscription runs $49–$144 a year (2026 prices); this is a file you own outright for $7.95.
Templates that implement this
Put your own numbers through the DRC math
1 template
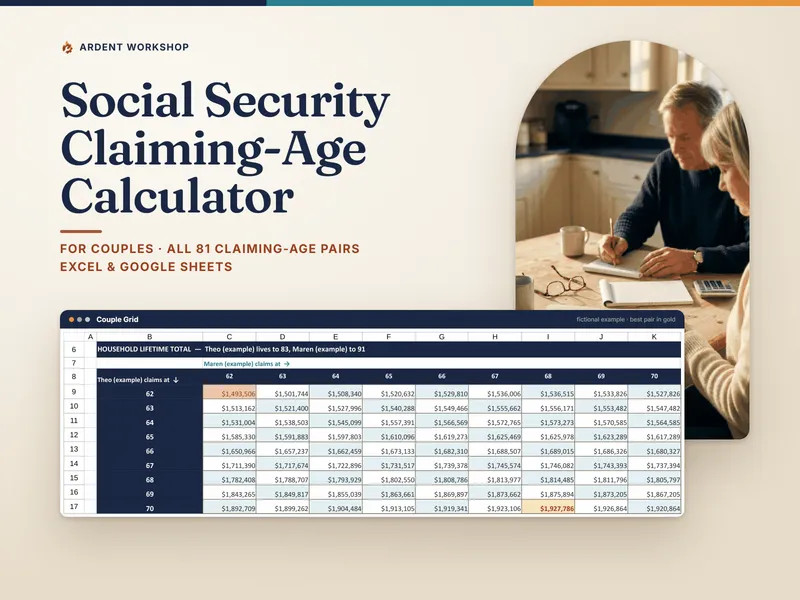
The Social Security Claiming-Age Calculator runs each person's benefit at every age 62 to 70 from the figure on your own statement, then totals all 81 claiming-age pairs for a couple — spousal top-up and survivor step-up included — against 49 death-age scenarios, with every rule shown and cited.
Frequently asked questions
- How much does a delayed retirement credit add to a check?
- 2/3 of 1% for every month you wait past your full retirement age, up to age 70 — 8% for a full year of waiting (POMS RS 00615.692). Wait the whole span available to you and the total tops out at 32% if your full retirement age is 66, or 24% if it's 67, because a later full retirement age leaves fewer months in which to earn credits.
- When do delayed retirement credits start and stop?
- They're earned from your full-retirement-age month through the month before you turn 70 (POMS RS 00615.692). Once you turn 70, waiting longer adds nothing — Social Security stops crediting further delay at that point (POMS RS 00615.690).
- When do delayed retirement credits actually show up in the payment?
- Generally the January after the year they were earned, or at 70 if you're already claiming by then (POMS RS 00615.690, RS 00615.692). A credit earned partway through a year doesn't appear in that year's check — it shows up starting the following January.
- Do delayed retirement credits increase a spousal benefit?
- No — and this is the rule that is easiest to get backwards. DRCs raise the worker's own retirement benefit (POMS RS 00615.695: "DRCs only increase the NH's RIB") and, because a survivor is paid 100% of what the worker was receiving, DRCs included, they raise the survivor benefit too (POMS RS 00615.301). They never raise a spousal benefit paid on that worker's record while both people are alive — a spouse's benefit tops out at up to 50% of the worker's full-retirement-age amount no matter how long the worker waited past full retirement age (POMS RS 00615.201).
- Is it worth waiting past age 70 to claim Social Security?
- No — delayed retirement credits stop the month before you turn 70, so there's nothing left to earn by waiting longer (POMS RS 00615.690). Claiming at 70 captures the full credit; delaying further only delays the check.
- Does everyone earn the same maximum delayed retirement credit?
- No — the maximum depends on your full retirement age, because that sets how many months sit between full retirement age and 70. Anyone with a full retirement age of 66 (born 1/2/1943 through 1/1/1955) has 48 months to earn credits at 2/3 of 1% a month, for a 32% maximum; anyone with a full retirement age of 67 (born 1/2/1960 or later) has 36 months, for a 24% maximum (POMS RS 00615.692, RS 00615.003).