Break-even is the age at which the bigger check you get for waiting has paid back everything you gave up by not claiming earlier. Claim at 62 and you start collecting right away, at a permanently reduced rate. Claim at 70 and every check afterward is bigger — but you gave up eight years of smaller checks to get there. Break-even is the point where the “bigger, later” pile of dollars finally catches up to the “smaller, sooner” pile. Before that age, claiming early has paid you more in total. After it, waiting has.
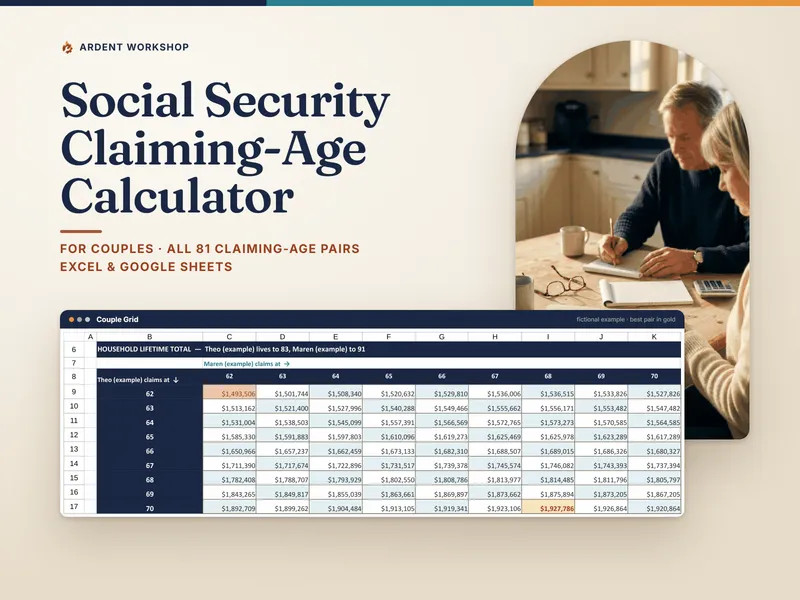
That crossing point is a straightforward calculation from two numbers most people already have — the monthly benefit at each claiming age, straight off a my Social Security statement — and the Social Security Claiming-Age Calculator runs the full version of it, for one person and for a couple, without ever estimating a benefit for you: you type in the figures your own statement gives you, and it does the arithmetic. If you want one person’s numbers at every age first, the free Social Security Claiming-Age Table is a spreadsheet you download and fill in on your own machine. Two terms do most of the work below: full retirement age, the age your unreduced benefit is paid, and the delayed retirement credit you earn for every month you wait past it.
How to work it out by hand
Say the earlier claiming age pays E a month, the later one pays L a month, and the two ages are M months apart. By the time the later age starts paying, the earlier claim has already collected E × M. Once both checks are running, the later one out-earns the earlier one by L − E every month. Divide the head start by that monthly gap, and add the result to the later age:
Break-even age = the later claiming age + (E × M) ÷ (L − E) months
The workbook’s fictional example couple, Theo and Maren, is a clean case to run it on. Theo’s full-retirement-age benefit is $2,860 a month; at 62 he’d be paid $2,013, and at 70, $3,546. Comparing those two ages, step by step:
- Get the monthly benefit at each of the two claiming ages. Pull the actual number from your own my Social Security statement or its online estimator — never estimate it yourself. Here that’s $2,013 at 62 and $3,546 at 70.
- Find how many months of head start the earlier age has. The two ages are 8 years apart, or 96 months, so the early claim has already collected 96 × $2,013 = $193,248 by the time the later check starts.
- Find the monthly gap between the two checks. $3,546 − $2,013 = $1,533 a month. That is how fast the later check makes up ground once it starts paying.
- Divide the head start by the monthly gap. $193,248 ÷ $1,533 is about 126 months, or 10 years and 6 months.
- Add that to the later claiming age. 10 years 6 months after age 70 is roughly age 80 and a half — close to the workbook’s own figure of 80 years 5 months.
- Treat the answer as one person’s number, not a couple’s. It compares one person’s own two checks. It says nothing about a spousal top-up, which never grows from waiting past full retirement age, or about a survivor benefit, which can carry the larger check to a second person for the rest of their life.
Cumulative Social Security totals at 62 versus 70
Here’s what each path has actually paid Theo, in total, at a run of ages — the numbers the hand calculation is built from:
| Age | Total paid if claimed at 62 | Total paid if claimed at 70 | Which claim is ahead |
|---|---|---|---|
| 62 | $0 | $0 | Tied |
| 65 | $72,468 | $0 | Claiming at 62 |
| 70 | $193,248 | $0 | Claiming at 62 |
| 75 | $314,028 | $212,760 | Claiming at 62 |
| 78 | $386,496 | $340,416 | Claiming at 62 |
| 79 | $410,652 | $382,968 | Claiming at 62 |
| 80 | $434,808 | $425,520 | Claiming at 62, by $9,288 |
| 80 years 6 months | about $447,000 | about $447,000 | Crossover |
| 81 | $458,964 | $468,072 | Claiming at 70, by $9,108 |
Through Theo’s late 70s, claiming at 62 stays ahead in flat dollars, by tens of thousands — eight extra years of checks is a lot of ground for a bigger check to make up. The two lines cross around age 80 and a half, and from there on, every additional year of life adds more to the 70-claim total than the 62-claim total, because the monthly gap between the checks never closes.
Why a COLA assumption moves the number
The flat-dollar comparison of Theo’s two claiming ages assumes no cost-of-living adjustment is ever applied to either check. That is not realistic: Social Security has applied a COLA in each of the last several years — 8.7%, then 3.2%, then 2.5%, and for December 2025 2.8%, payable from January 2026 (POMS RS 00601.120 (opens in new tab)). Once a COLA is applied it lands on both checks as the same percentage, not the same dollar amount. A percentage raise on the bigger check is a bigger dollar raise than the same percentage on the smaller one, so the monthly gap between the two checks — the number doing the work of closing Theo’s $9,288 lead — grows a little wider every year a COLA is applied, instead of staying fixed at $1,533. A wider, growing gap closes a head start faster than a flat one does, which is the direction a COLA assumption generally pushes a break-even age: earlier, not later. How much earlier depends on the COLA rate assumed, which is exactly why the workbook makes it a setting you choose rather than a number it assumes for you.
Why break-even is the wrong question for a couple
A break-even age compares one person’s own two checks against each other, and for a single person claiming on their own record, that’s the right comparison. For a married couple, it leaves out the two things that matter most.
The first is the survivor benefit. When one spouse dies, the survivor doesn’t keep their own check and lose the other’s — they step up to whichever check was larger, including any delayed retirement credits it earned, for the rest of their own life (POMS RS 00615.301 (opens in new tab)). If Theo delays to 70 and dies first, Maren doesn’t just get her own benefit; she can step up to Theo’s $3,546 for as long as she lives — not just until Theo’s personal break-even age arrives. Two survivor rules shape what she actually receives: a survivor benefit claimed before her own survivor full retirement age is reduced, down to 71.5% of the full amount if she claims it as early as 60, and where the person who died had claimed early, the widow(er)‘s limit caps it at the larger of their reduced benefit or 82.5% of their primary insurance amount (POMS RS 00615.320 (opens in new tab)). Either way, a break-even age computed on Theo’s numbers alone says nothing about how many years Maren might collect the larger check afterward, and that is very often worth more than Theo’s own break-even math suggests on its own.
The second is that a spousal top-up earns no delayed credit at all. Delayed retirement credits raise a worker’s own benefit, and they raise what a survivor can step up to — but they never raise a spousal benefit (POMS RS 00615.695 (opens in new tab): “DRCs only increase the NH’s RIB”), which is capped at up to 50% of the other spouse’s benefit at full retirement age regardless of how long that spouse waits past it (POMS RS 00615.201 (opens in new tab)). If Maren is claiming a spousal top-up rather than her own record, there’s no version of “wait longer” that grows her spousal check the way it grows Theo’s own.
So for a couple, the honest question isn’t “which of my two claiming ages breaks even sooner” — it’s “which claiming ages, for both of us, produce the best result across the years either of us might live, including the years one of us might live alone on the other’s check.” That’s a different calculation, run across every combination of two claiming ages and tested against a range of how long each spouse might live — which is what the paid workbook does that a single break-even age can’t.
Where the claiming-age calculator fits
This walkthrough runs one person’s break-even by hand, on one worked example. The Social Security Claiming-Age Calculator runs the couple’s version: all 81 claiming-age pairs for the two of you, totaled at the ages you set and tested against 49 combinations of death ages, survivor step-up and spousal top-up included, with every rule shown and cited — you type in the benefit figures from your own statement, and it never estimates one for you.
The free Social Security Claiming-Age Table is a smaller, single-person, pre-filled version — the benefit at every age from 62 to 70 off one full-retirement-age figure — if you want to see your own numbers at each age before deciding whether the couple’s break-even and survivor math is worth running. If the terms underneath all of this are the part that’s unclear, start with what full retirement age is and what a delayed retirement credit is.