
What it is, in one paragraph
A repair credit is a dollar amount the seller agrees to contribute at closing, in lieu of arranging and paying for a repair before the sale closes. The credit reduces what you bring to closing or adds to the cash you walk away with, and you take on the repair afterward — hiring the contractor, scheduling the work, and paying them out of that credit. It is one of two routes a home-inspection finding can take between buyer and seller; the other is the seller arranging and paying for the repair directly before the sale closes.
Why a buyer might prefer a credit
The main reason is control. A repair arranged by the seller under a closing deadline is a repair chosen by someone who has little reason to pick the best contractor, or to insist on the best materials, for a house they are about to no longer own. A credit lets you choose who does the work, when, and to what standard — after the pressure of a closing date is gone.
It can also simplify a closing that is already carrying several negotiated items: one number, rather than a list of repair commitments to verify before you close.
Why a buyer might not
A credit converts a problem the seller was going to handle into a project you now own. The money has to actually cover the work — quotes can run over an inspection-time estimate, and a finding that turns out to be worse once a contractor opens the wall is now your finding, not the seller's. You are also holding the credit as a number on a closing statement, not as cash in a bank account, until closing itself happens; if the deal falls through beforehand, the credit is not something you were ever paid.
Your loan program may cap how large a credit can be
A seller credit is typically recorded as a seller concession on the closing disclosure — confirm with your lender how yours would be treated. Loan programs may cap concessions as a percentage of the purchase price; where a cap applies it can vary by loan type and by how much you are putting down, and some programs draw a line between a credit tied to repairs and a general concession toward closing costs. Ask your own lender what your program allows before you negotiate a specific number — a credit larger than your loan program permits may have to be reduced or restructured at closing, which is not something you want to discover at the closing table.
A credit is negotiated, never automatic
Nothing in an inspection report obligates a seller to offer a credit, a repair, or anything else — what a contract entitles you to ask for, and by when, is set by the inspection contingency you signed, and what a seller agrees to is a negotiation, not a formula. Whether a credit or a seller-arranged repair makes more sense for a given finding can depend on the finding itself: something that affects financing or insurability may need to be resolved one way or the other before the loan can close at all, regardless of which route you'd otherwise prefer.
Pricing the choice instead of guessing at it
The comparison is easiest to make finding by finding rather than as one lump judgment: what a credit is worth to you against your lender's cap and the cash you have left to close, against what a seller-arranged repair under deadline pressure is worth to you as a finished job.
You can start free. The Home-Inspection Findings Triage Sheet is a printable worksheet — no email, no signup — that sorts each finding into deal-breaker, negotiable or cosmetic from the inspector's severity and the kind of problem it is. It carries no cost data at all: it sorts findings, it does not price them, and it does no ask math and builds no letter.
Pricing the credit-versus-repair choice is what the paid Home-Inspection Review & Repair-Negotiation Worksheet adds. Every finding you log is priced from a built-in library of 126 curated repair items across 12 home systems — wide low/typical/high planning bands, scaled by a regional index you can overwrite and replaced by your own contractor's quote the moment you have one — then sorted by rule into one of four tiers (deal-breaker, major cost, negotiable, cosmetic) instead of by gut. It runs the credit-versus-repair comparison for your shortlisted findings against your own cash-to-close and your lender's credit cap, lists and totals what you are choosing to absorb, and assembles the request letter itself. Eight tabs in Excel, Google Sheets or LibreOffice, plus three printable PDF guides — a file you own outright for $14.95, not a subscription. Own it, don't rent it.
For the whole method — setting your thresholds before you read the report's tone, pricing every finding, and netting the total ask against the cash you actually have left — see what to ask for after a home inspection.
Related concepts
A repair credit only exists because of the contingency that lets you negotiate at all — see what earnest money is for how that same contingency determines whether your deposit is refundable. For how scope changes get priced once you own the house and the work starts, see what a change order is. For the decision behind the purchase itself, the Big Decisions workbooks score it before you get to a contract.
Templates that implement this
Tools for turning a findings list into a request
3 templates
A worksheet that prices and triages the findings themselves, and the checklist and calculator for the contract and the ownership costs around them.
- $14.95 Spreadsheet

Home-Inspection Review & Repair-Negotiation Worksheet — Price Every Finding, Then Build the Ask (Excel & Google Sheets)
Turn a home-inspection report into a costed, prioritized repair ask — every finding priced from a built-in library and netted against your cash to close.
Big DecisionsView details - $14.95 Spreadsheet

Contract & Deposit Red-Flags Review Checklist — 180 Clause Checks Across Six Contract Types, Scored, With a Deposit & Cancellation Tracker (Excel & Google Sheets)
180 curated contract red flags across venue, lease, contractor, home, vehicle and membership agreements — scored, with a deposit and cancellation tracker.
Big DecisionsView details - $14.95 Spreadsheet
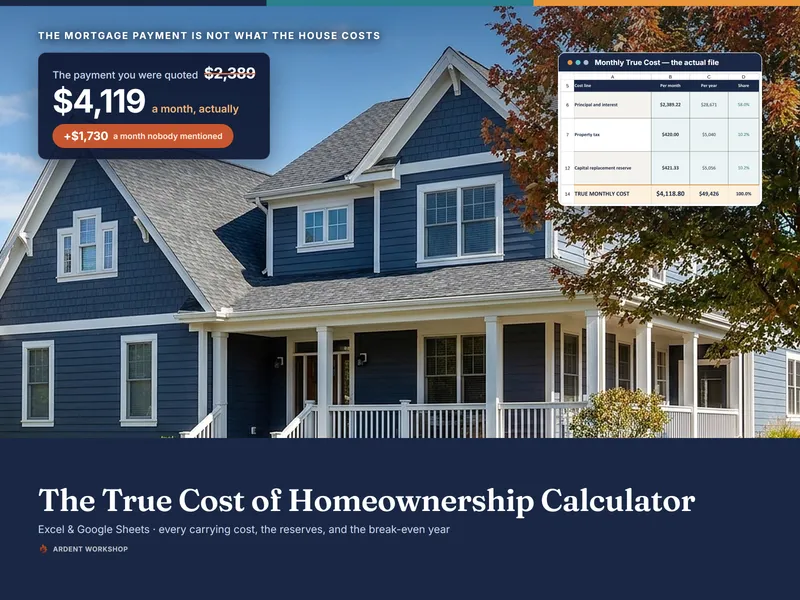
True Cost of Homeownership Calculator — Every Carrying Cost, the Replacement Reserves & the Buy-vs-Rent Break-Even Year (Excel & Google Sheets)
Find what a specific home really costs per month — the mortgage payment plus the seven lines listing sites leave out — and the year owning beats renting.
Big DecisionsView details